Insights Valuation 7 min read
Normalised EBITDA: the add-backs buyers accept, and the ones they don't
The number a buyer multiplies is not the EBITDA in your accounts. Here is how the adjustments work, with the evidence each one needs.
By the Sightline partners ·
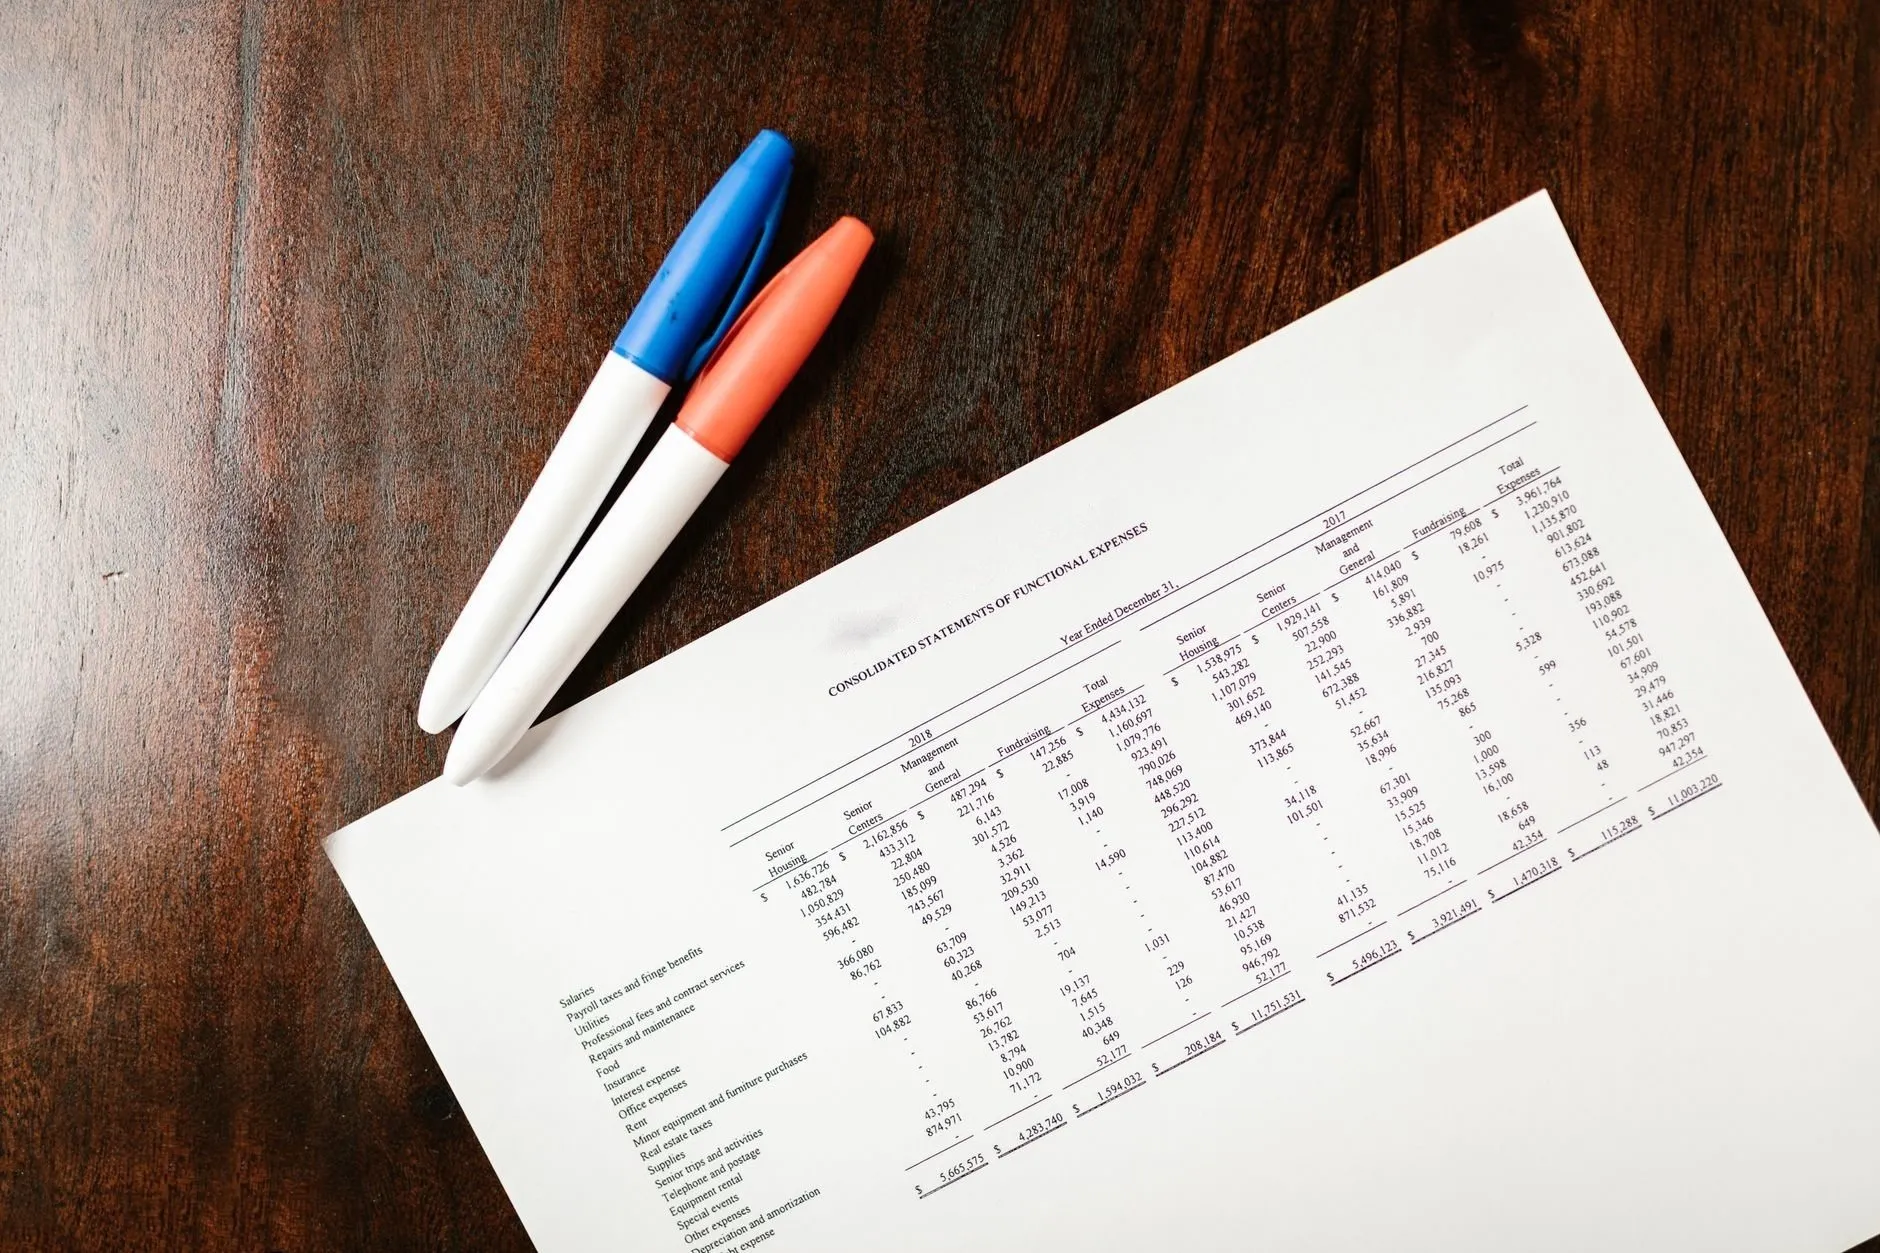
When a buyer says they will pay “six times EBITDA”, they do not mean the EBITDA in your statutory accounts. They mean normalised EBITDA: what the business earns once the costs that will not continue under new ownership are taken out, and the costs that are missing are put in.
The difference is often 10–25% for an owner-managed company. At six times, every $100,000 of accepted add-back is worth $600,000 of price. It is the most valuable spreadsheet you will ever build, and it is the one most owners leave to the buyer.
Add-backs buyers usually accept
Owner pay above market. If you pay yourself $450,000 and a hired managing director would cost $250,000, the $200,000 difference is added back. You need a salary benchmark, not an opinion.
Genuine one-offs. A lawsuit settled, a move to new premises, a system implementation. Buyers accept these when the cost is clearly bounded and has not happened three years running.
Related-party costs at non-market rates. Rent paid to a property company you own, or a family member on the payroll who does not work in the business. The adjustment works in both directions: below-market rent is a deduction.
Add-backs buyers push back on
“Recurring one-offs.” A bad-debt write-off every year is not a one-off. Neither is a recruitment fee in a company that hires every quarter.
Costs you cut just before the sale. Stopping marketing for six months increases EBITDA and is spotted immediately. Buyers will add the cost back in.
Projected savings. Synergies belong to the buyer. They will not pay you for savings they have to deliver.
What the evidence looks like
For each adjustment: the ledger entries, the invoice or contract, a one-paragraph explanation and, for pay, a benchmark. We put these in a single schedule that ties back to the audited accounts, so a buyer’s accountant can tick through it in an afternoon rather than challenging it over a month.
If you want a first view of where your number might land, the valuation estimator gives an indicative range on reported figures. The normalisation is what moves you within, or above, that range.
Quick answers
- Is normalised EBITDA the same as adjusted EBITDA?
- In practice, yes. Both mean reported EBITDA with one-off, owner-related and non-market items removed so a buyer sees the earnings the business will produce under new ownership.
- Who checks the add-backs?
- The buyer's accountants, in a quality-of-earnings review. Every add-back without evidence is at risk of being struck out, and each dollar struck out costs you the multiple.